Fintech
Sep 30, 2026

Private markets are entering a period of rapid change, as capital, technology and regulation reshape the infrastructure supporting transactions across emerging markets. Zest Equity co-founders Zuhair Shamma and Rawan Baddour discuss what comes next.
[For more news, click here]
The financial landscape around emerging markets is changing quickly, with new institutions, investors and technology companies increasingly shaping how capital moves through the region. For businesses operating within that environment, the shift is creating a different kind of opportunity, one that sits between established financial practice and a more technology-led generation of market infrastructure.
Zuhair Shamma and Rawan Baddour, have experienced that transition from different sides of the financial industry. Shamma spent more than a decade across investment banking and private equity, while Baddour built her career of more than 12 years across strategic advisory, banking and finance. Their paths eventually converged at Zest Equity, where they have spent the past several years building within the private markets ecosystem.
In this exclusive interview with Tech Revolt, they reflect on what they have learned from that experience and where they believe the financial industry is heading next.
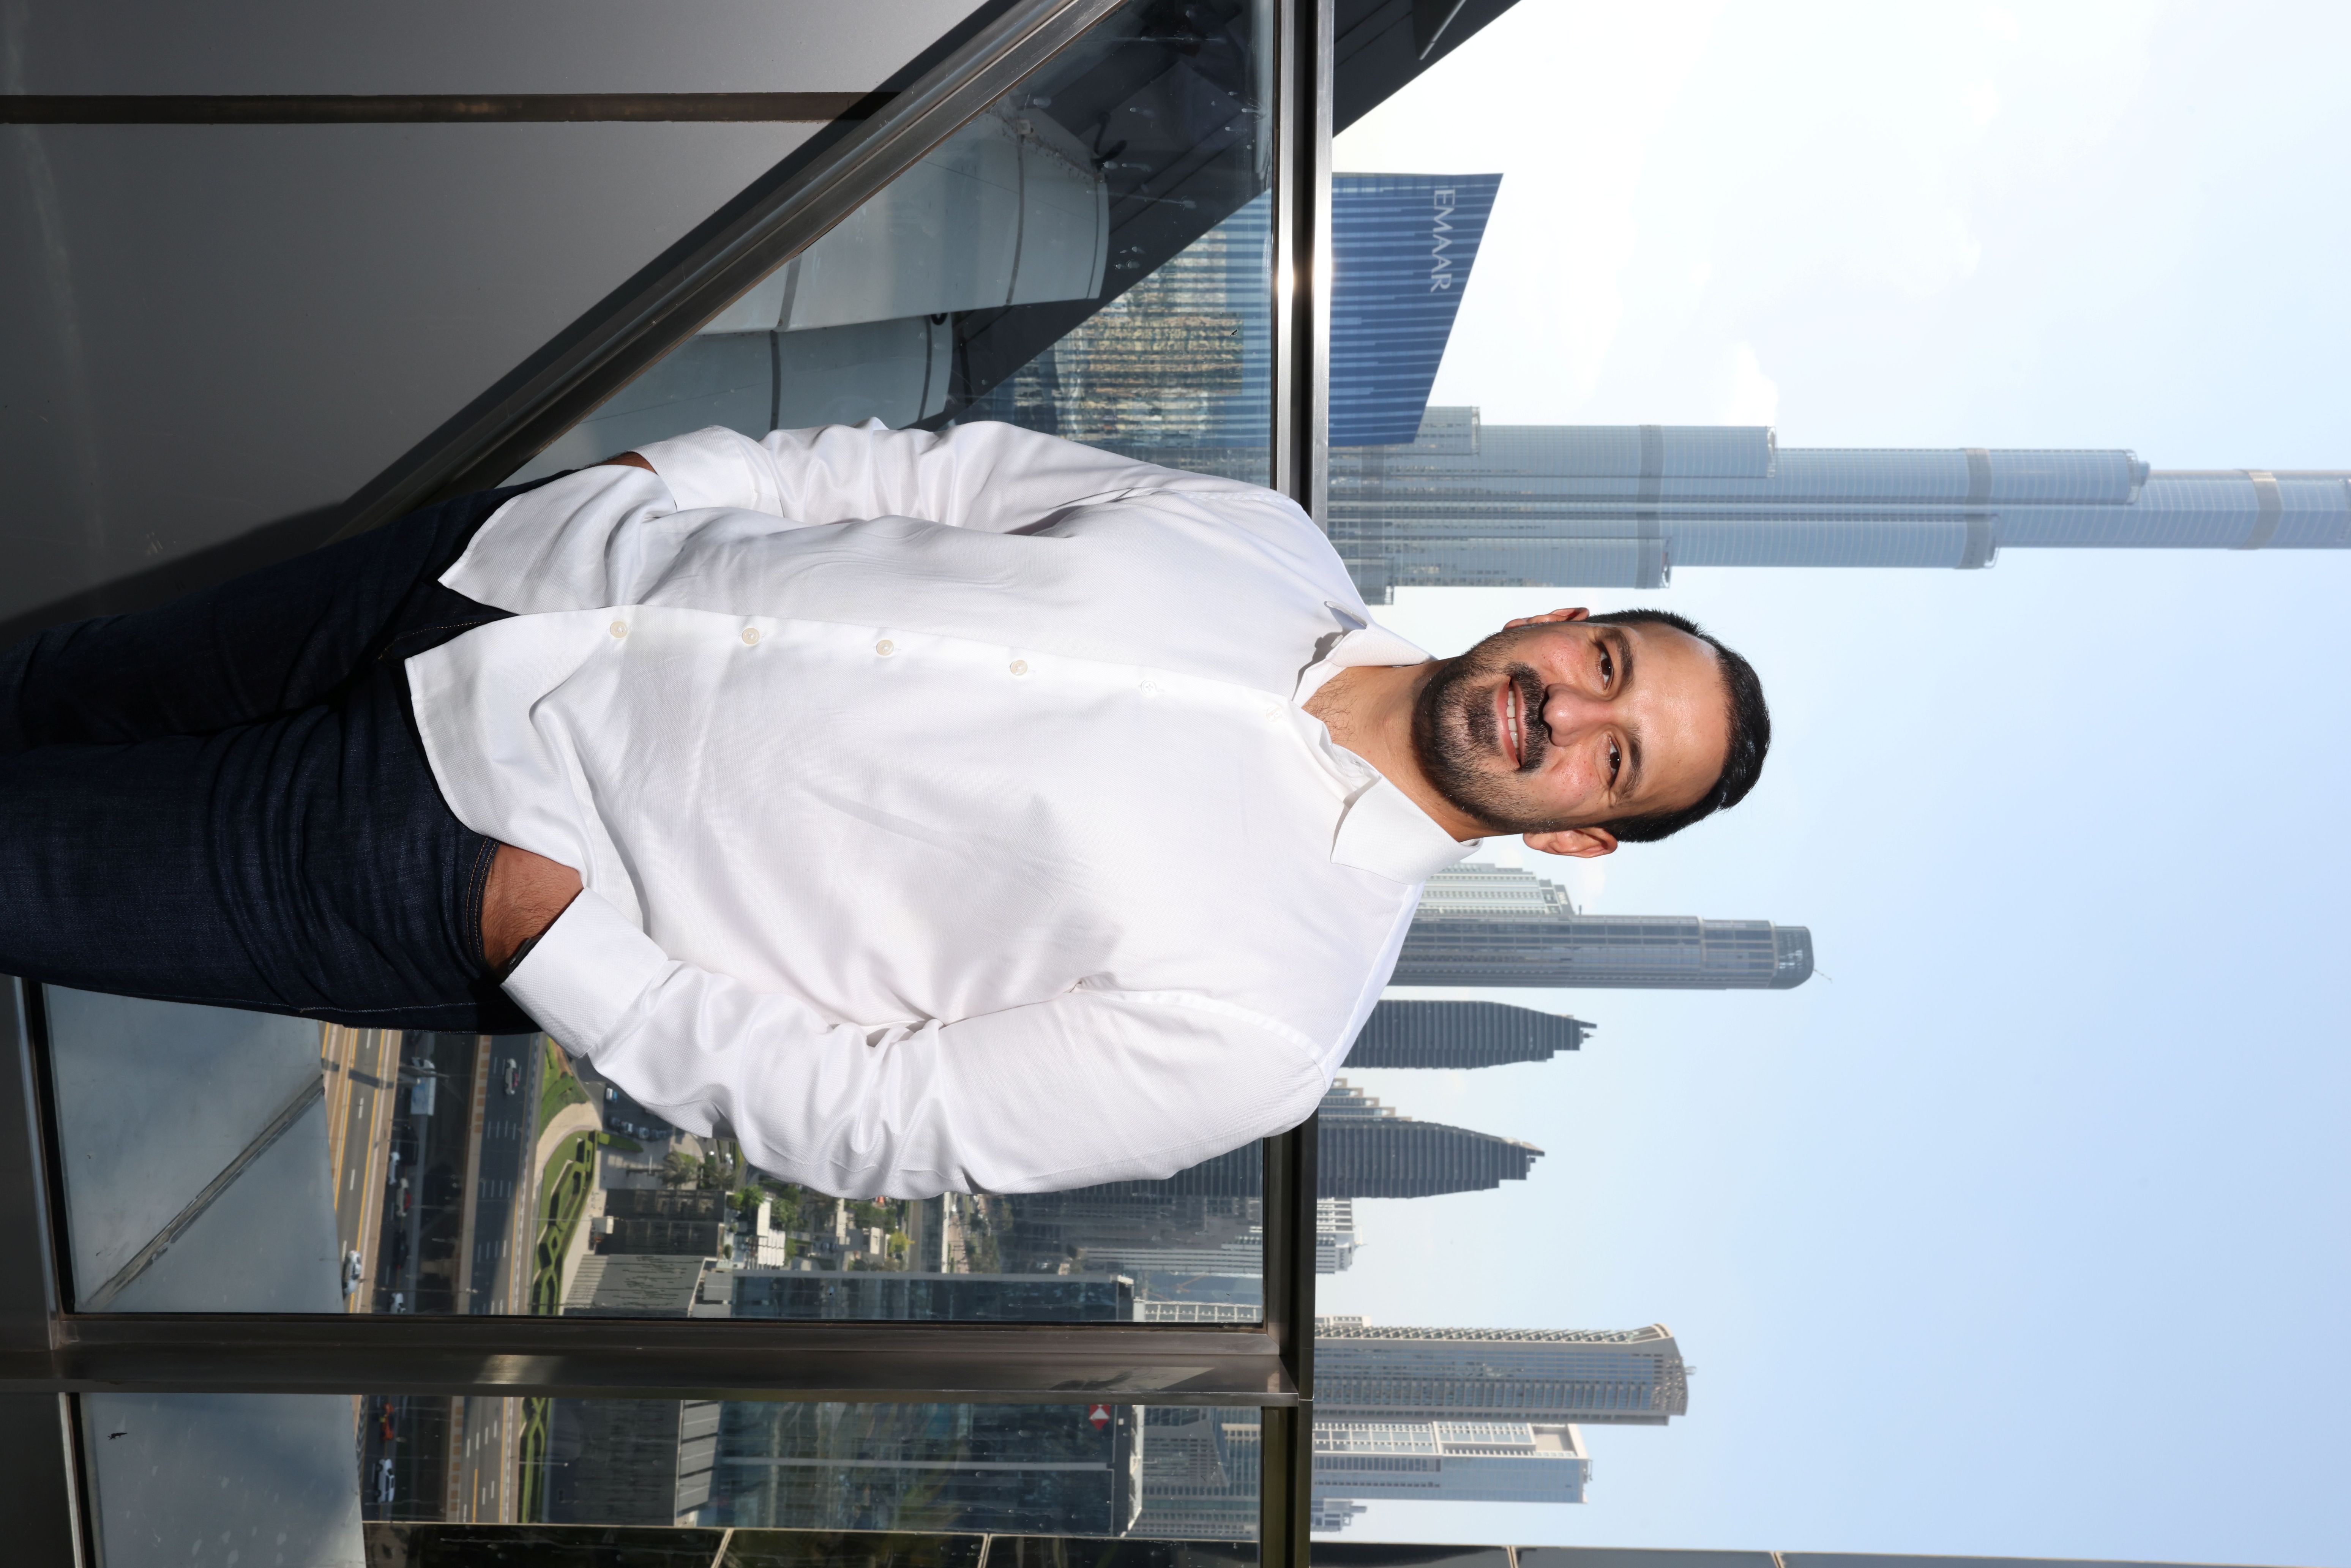
Zuhair Shamma
Co-Founder & CEO, Zest Equity
Q1. Where does the biggest infrastructure gap actually sit today?
The gap is not in capital. It is in execution.
We learned that the hard way. Zest Equity did not start out solving the problem it solves today. We began with a liquidity thesis, helping early shareholders and companies access liquidity. Then we sat with deal makers, fund managers and founders, and every conversation pointed somewhere else. Liquidity was not the bottleneck. Execution was. People were losing hours chasing emails, WhatsApps, gathering documents and untangling the governance behind every single transfer.
When we analyzed hundreds of transactions, we found four pillars behind every one: investor management, execution capability, risk management, and portfolio monitoring. Each sits with a different party, on a different system, usually priced for a large ticket. That is why the friction is worse on smaller deals: manual processes make them uneconomical to serve. Roughly 96% of disclosed deals in this region in H1 2025 were under $100 million. That is where the market actually is.
Here is what 230+ transactions and $300M+ in deal value taught us: every deal looks unique on the surface, but the workflow underneath is nearly identical across transaction types and asset classes. Which means it can be built once and it scales. Transactions that once took months close in days, end to end, on infrastructure we own and operate. Effectively, what Stripe did for payments, we are doing for private market transactions.
Q2. What should we not digitize, because the process itself needs redesigning?
Three, specifically.
Investor onboarding. Digitizing the existing process just gives you the same repetition with a nicer interface. The redesign is onboard-once: verify an investor properly, then let that verification travel across deals, sponsors and jurisdictions. It is a different process, not a faster version of the same one.
Executing off documents. In private markets, the document is not just the record of the deal. It is also what runs it. The terms sit in the paper, and someone still has to update the register, check whether a transfer is permitted, and work out who gets what on a distribution. The redesign is to put those terms into the transaction itself, at the share and shareholder level, so the system enforces what the document says. Same agreement, same words. It just stops being the thing you operate.
Fund flows. Today money moves on somebody's word. A wire instruction goes out by email, and the sender has to trust that the other side has done what it said: shares issued, register updated, signatures in. Digitizing that gives you a faster email and exactly the same exposure. . Funds sit with a regulated third party, which releases them only when the conditions are evidenced and returns them if they are not. Nobody chases, nobody takes the counterparty's word, and the deal stops depending on goodwill when it matters most. That is a different process, not a faster one, and it is why we went and got the license to do it ourselves..
The pattern across all three is the same. Most of the work in a private deal is coordination. But coordination is not the thing to automate; it is the symptom. Investor management, execution, risk and monitoring are usually living in four different places. Put them in one place and the coordination disappears..
Q3. What changes when capital itself becomes a technology layer?
What changes is not the money. It is the conditions traveling with it.
Today, those conditions live outside the transaction. A term sheet says funds release when the shareholder register is updated and the escrow agent has confirmation. That is an instruction to a human, sitting in a PDF and executed by someone reading their email. Capital becoming a technology layer means those conditions stop being a description of what should happen and become the thing that actually executes.
We do a version of this already. Under our money services license in ADGM, Zest Escrow receives funds, holds them in segregated accounts, and releases them only when the agreed conditions are met. That is programmable capital in production. It just does not need a blockchain to be true.
So my view is that the "future of capital" conversation gets more useful when you move it off the asset and onto the rulebook. Whether the instrument is digital is secondary. What matters is whether the mandate, eligibility, permissions and release conditions are machine-readable and enforceable. That is what changes how capital behaves.
Q4. Tokenization: new products, or existing markets made dramatically more efficient?
There is a lot of energy going into what tokenization could create, and comparatively little going into what it could fix. I would take the fix. If you can take a transaction that takes months and close it in days, with every party onboarded once, funds moving against evidenced conditions and a record that holds up when the auditors and the next set of participants come looking, you have created more value than most new products will. We do that today, and there is no token in it.
Because you do not need one. You do not need a token to fix a process that runs across three spreadsheets, a lawyer's inbox and a bank transfer nobody can trace. You need structure, governance, and one workflow that every party in the deal is actually on.
The new products come, but they come second. Fractionalization, real-time secondaries, programmable distributions, none of that works on top of a market where investor onboarding is repeated from scratch for every deal and settlement is reconciled by email. Build the execution layer first. Then the product layer has something to stand on.
Basically: the boring version of this is where the money is.
Q5. How far are we from AI executing meaningful financial transactions autonomously?
We are already there for the work around the transaction. We are not close for the transaction itself, and I think that is correct.
We launched Tarth in June as our first full agentic deployment. It handles investor and entity compliance onboarding: reads the documents, runs the checks, and produces a compliance-ready recommendation with every point cited back to its source. Median case time went from about 60 minutes to 3 minutes, with more than 800 hours of compliance work saved so far. But a compliance officer still makes the determination. We think of it as an agent on the team rather than a piece of software.
What will resist autonomy longest is anything that transfers legal title or irreversibly moves money. Not because the models cannot do it, but because accountability has nowhere to sit yet. When an automated decision goes wrong, someone has to be answerable, and right now the answer in most institutions is "nobody has decided."
So, for now, AI will compress at least 75% of a deal that is just process, and the rest will stay human for some time. That is a governance timeline, not a capability timeline.
Q6. Five years ahead, what separates the markets that modernize from those that accumulate fintech?
One test, and you can apply it today.
Can you see, at any moment, who owns what, who verified whom, and where the money sits, without asking a single person? If yes, you have modernized. If you have to call someone, you have just bought software and the answer still lives in someone's head, not in the system.
Accumulating fintech is easy and it feels like progress. Every tool solves a real problem, but every tool adds an integration, a reconciliation and another place for the truth to live. Five years of that and you have more software and less certainty than when you started.
The markets that pull ahead will be the ones that changed where the record lives, not the ones that changed the interface on top of it. A single source of truth for the transaction, compliance built into the architecture rather than bolted on at the end, and settlement you do not have to trust anyone to perform.
Given that roughly $1 trillion in family-held wealth is expected to change hands across the GCC over the coming decade, the region does not have five years to decide. The capital is arriving now. The infrastructure should be there to meet it.
And for this region specifically, that is the whole opportunity: building the infrastructure that carries us from being a consumer of global capital to being a hub for it. You do not get to be a hub on manual processes.
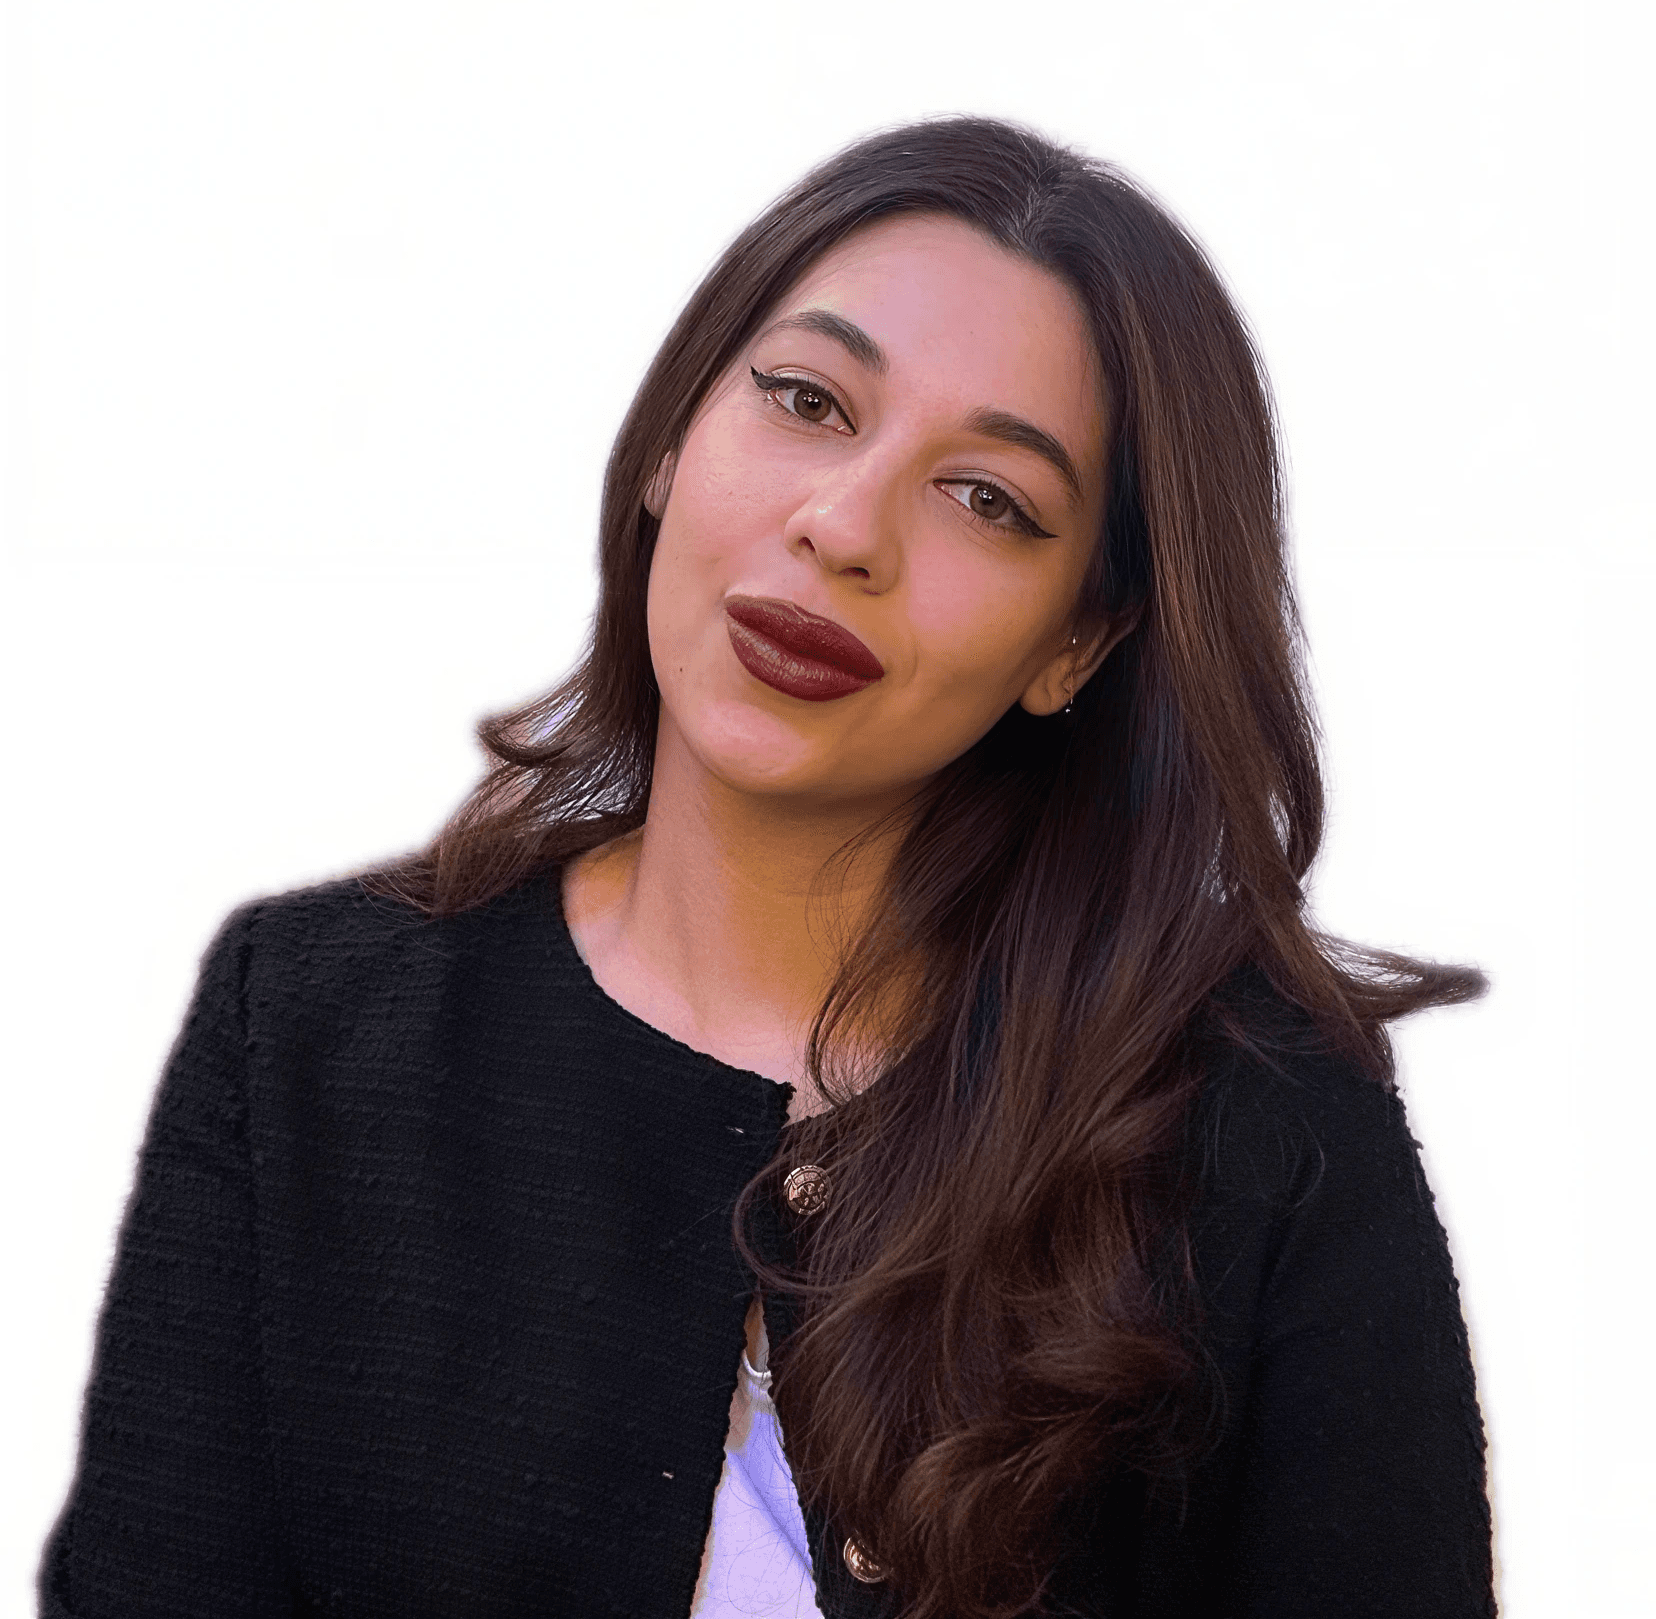
Rawan Baddour
Co-Founder, Zest Equity
Q1. Is trust becoming primarily a technology, regulatory or human problem?
I think it has always been all three, and the useful question is which one is currently binding.
There is a version of this question that treats trust as a technology problem: uptime, encryption, verification, fraud controls. That matters, and it is the version the industry is most comfortable with because it has a roadmap. What I find more meaningful is that trust in financial services rarely breaks because a system failed. It breaks because nobody can explain how a decision was reached, whether the right guardrails were in place, or who was answerable for it.
That makes it an accountability problem before it is a technology problem. Technology determines what can be traced, prevented and reconstructed afterwards. Regulation determines where responsibility sits when something goes wrong. But the decision to extend trust, whether by an institutional investor, counterparty or regulator, remains a human judgment about whether the people on the other side will stand behind what their systems produce.
For a region attracting capital from around the world, sustainable growth needs trust, reliability and streamlined execution together, inside workflows with the guardrails to prevent failures rather than explain them afterward. Those are not separate agendas. Manual and informal execution is precisely what makes trust unverifiable, because nothing about it can be reconstructed.
That is the most consistent thing we have observed across several hundred transactions. No deal completes because the technology was impressive. It completes because every participant can see how the process works and who stands behind it.
So my answer is that automation has not moved trust from the human column to the technology column. It has raised the standard of evidence humans now require before they will extend it.
Q2. Give me an example, what does trust by design actually look like at the moment software, not a person, makes the call?
It looks like reconstructability, and not in an abstract sense.
There is a version of trust by design that stays at the level of disclosure; consent screens, terms, a policy page confirming that controls exist. I understand why that has become the norm, because it is auditable and cheap. What I find more meaningful is whether a specific decision, taken by a specific system, on a specific day, can be reopened months later and understood by three different parties who each have a reason to disagree.
That is the standard we hold ourselves to. Tarth, the AI compliance agent we put into production in June to handle investor and entity onboarding checks, cites every decision it produces back to the document, the database, or the rule that drove it. A compliance officer, a client and a regulator can each follow the same trail and reach the same conclusion or identify precisely where they would have decided differently. That last part is the point. Trust is not the absence of disagreement; it is the ability to locate it.
Practically, this means compliance has to live inside the architecture rather than being applied at the end. A system that was designed to be explained behaves differently from one that is explained after the fact.
Q3. Who is accountable when an automated system makes a consequential financial decision?
With the institution that acted on the output. Not the model, not the vendor, and not the individual who happened to be closest to the screen.
That is easy to state and harder to operationalize, because accountability is only real if the person carrying it has a genuine opportunity to refuse. A human approval on a recommendation that cannot be inspected is not oversight; it is the appearance of oversight. It distributes blame without distributing understanding.
This is why the design question and the governance question are the same question. We built our compliance agent to produce a recommendation with its evidence attached, every conclusion cited to the document, database or rule behind it, so the compliance officer making the final determination has the room to challenge it, make judgments and rerun the analysis with new information. Where a human cannot meaningfully accept, reject, challenge or guide the conclusion, the process should not be automated yet.
Regulation will formalize this over time, and I think accountability should sit with the authorized entity. Firms that decide now who carries that accountability will find that the eventual rules simply describe what they are already doing.
Q4. How can space be created for experimentation without "move fast and discover the risks later"?
From what I have observed, the distinction that matters is between experimenting with the product and experimenting with the safeguards. The first is legitimate and necessary. The second is where "move fast" becomes a problem, and the two get conflated more often than they should.
Sandboxes and phased authorizations work well when their boundaries are drawn around exposure rather than technology: how many counterparties are affected and how reversible a failure is. When they are drawn around novelty instead, you can end up permitting risky activity because it is new while obstructing safe activity because it is familiar.
Our own experience going through FSRA authorization in ADGM shaped this view. It required a stricter and more deliberate build from day one, with transparency, visibility and auditability built into the core workflows rather than added once we had scale to justify them. At the time, that is demanding. In retrospect, it functioned as a specification rather than a constraint: it told us what the product had to be able to prove.
The direction of travel in this region is right. Frameworks are being written by regulators who assume digital execution rather than accommodate it, and that materially changes what is possible to build.
Q5. What is the biggest misconception the fintech industry still has about compliance?
That it is a gate applied at the end, rather than an integral component of the systems being designed.
The framing I hear most often is that compliance slows innovation down, and I understand where it comes from. Reviews take time, and authorization processes are demanding. Building the controls properly costs something, but getting it wrong costs far more, which is why compliance is a condition of sustainable growth rather than a tax on it.
What I find more meaningful is what compliance actually enables. In private markets, institutional allocators, international LPs and regulated intermediaries will not transact on infrastructure that cannot evidence how it behaves. Compliance is not what limits the addressable market. It unlocks the part of the market that will sustainably grow.
There is a second effect that gets less attention. Manual compliance carries a fixed cost per stakeholder, which is why smaller deals have historically been uneconomical for providers to serve. Building those controls into the platform changes the economics, making a segment of the market servable that previously was not. That is not compliance constraining innovation. That is compliance creating the market.
Our own onboarding process did not slow the product down. It defined what the product had to be able to prove, and the platform is better for having answered those questions early.
Beyond Digitization
The conversation between Shamma and Baddour ultimately points to a broader transition underway in private markets. The next generation of infrastructure will be judged not only by how quickly transactions move, but by whether the systems behind them can make ownership, evidence, responsibility and settlement visible and repeatable.
For emerging markets, that means the opportunity is no longer simply to digitize existing financial processes. It is to build the infrastructure around them in a way that can support increasingly complex capital flows while preserving the governance and accountability expected by the institutions participating in them.
Related Articles
Exclusive: Zuhair on Building Trust and Scale in Emerging Market FinTech
Exclusive: Célia Hassid on the New Rules of AI in Banking
Banks accelerate AI adoption but trust gap persists globally
Related Articles