Fintech
Sep 23, 2026
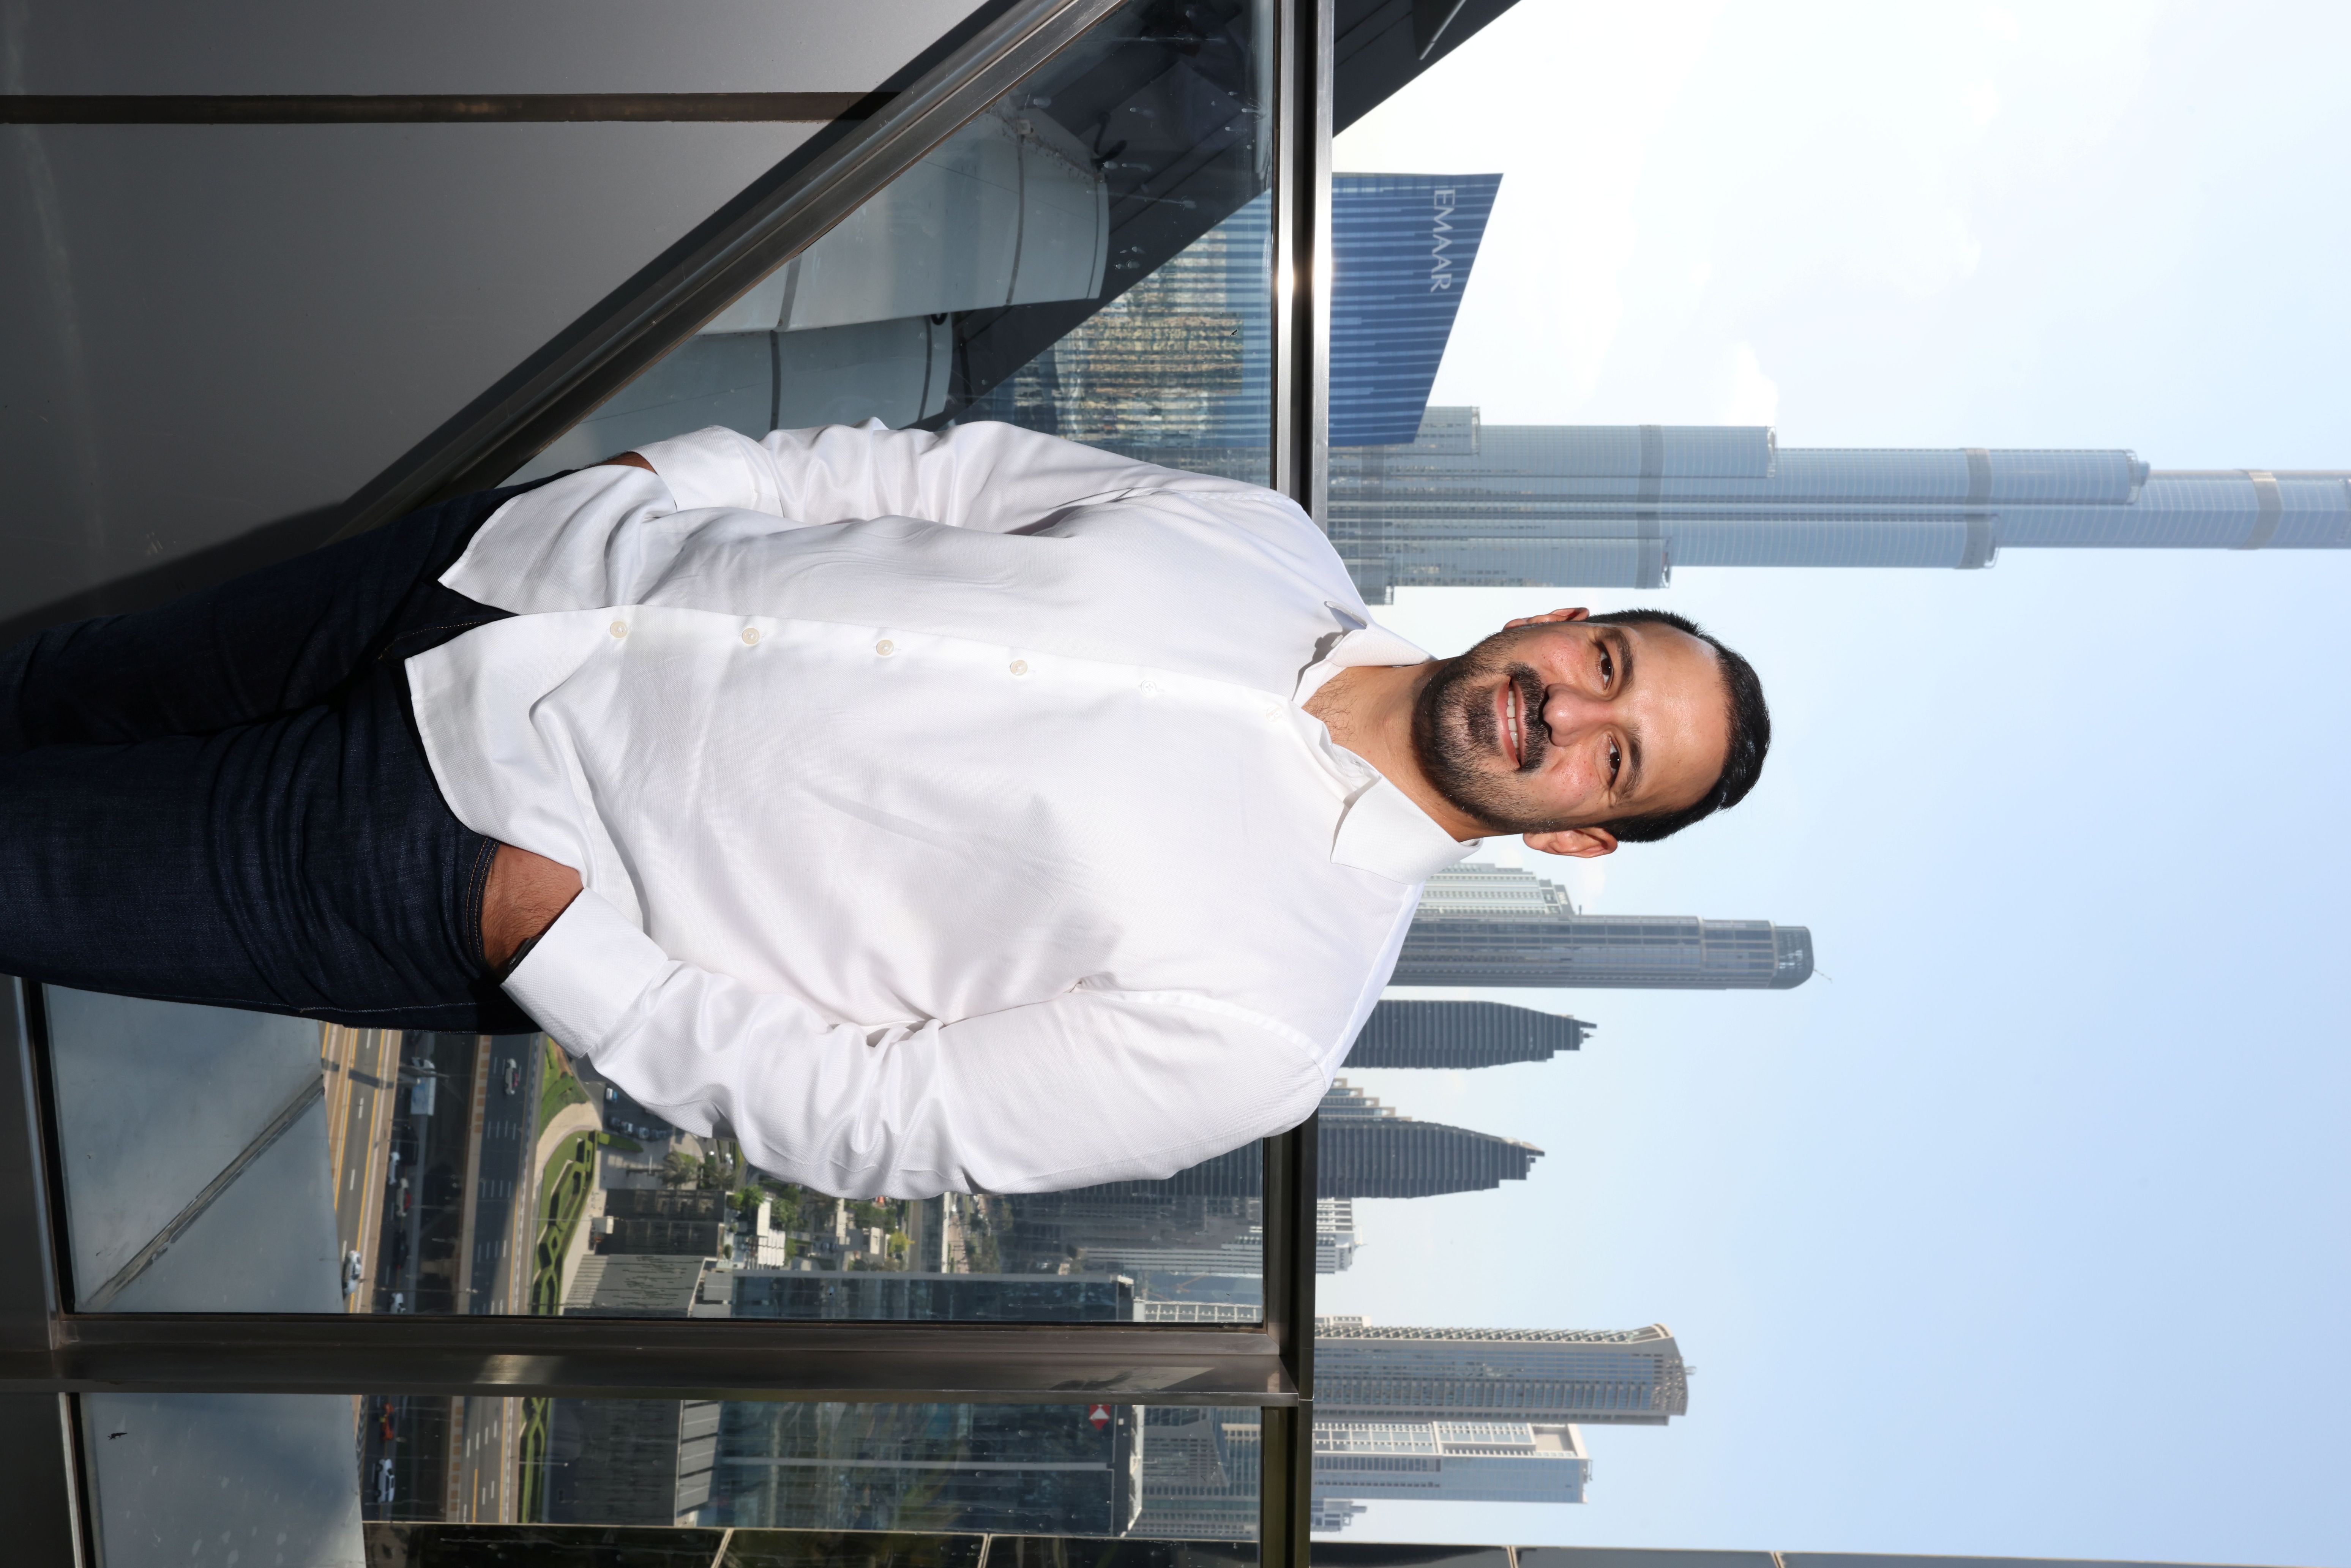
Ayham Gorani is Co-Founder and CEO of Pemo, an all-in-one spend management platform built for SMEs. Born in Germany to Syrian parents, he is a computer scientist and entrepreneur who built and sold his first company before moving to the UAE in 2011. He co-founded Pemo in 2022.
[For more news, click here]
The UAE’s spend management space has quickly become one of the region’s most crowded fintech categories. From corporate cards and expense automation to invoice payments, a cluster of well-funded startups is competing for the same SME wallet. Pemo is already part of that race, having raised 19 million dollars across two rounds. That figure is lower than rivals such as Alaan and Qashio, but the company has still earned a place on Forbes Middle East’s Fintech 50 and secured in-principle approval from the Central Bank of the UAE for a Stored Value Facilities licence.
Pemo’s story is not about outspending the market. It is about a founder who has built companies before, made expensive mistakes, and become almost evangelical about doing less, more deliberately: validating ideas cheaply, killing them quickly, and keeping the team lean.
As Pemo moves beyond spend management and works toward becoming a broader financial platform for SMEs, Tech Revolt spoke with Ayham Gorani about the discipline behind that growth, why he believes being out-raised made Pemo stronger, and what he would tell other founders trying to build with restraint.
Discipline Over Capital
Q1. You were born in Germany to Syrian parents, studied and started your first company there, and are now building in the UAE. How did that journey unfold?
I spent most of my life in Germany. I studied there and started my first company, which I sold when I was 27. At that point, I wanted to see something new. I was weighing the West, meaning the US and Silicon Valley, against this region. I visited Abu Dhabi and Dubai to understand what was happening here and was introduced to someone in a free zone who was just starting a VC fund. He told me I should set up here because there would be plenty of opportunities for someone who understood technology. Given my roots, it was a no-brainer. I found the region exciting and felt there was a lot to build, whether in Arabic content or the broader digitisation of the market.
Q2. You have called meeting your co-founders your lucky moment. But too many cooks can spoil the broth, and you were not a first-time founder. How did you find alignment and avoid conflict?
Looking back, I learned that structure matters enormously: how you set up a company, and how you build the right culture and mindset inside it. I have had two kinds of co-founder experiences. The first was Alpha Apps, which I started with someone related to me. We had known each other for years, so that collaboration was built on trust. We complemented each other well, which made alignment easier. With Pemo, I had co-founders I had never worked with and did not know well. That setup required a different kind of work, and I underestimated how important it was to define the real vision before you start. Today, I believe that sits at the core of the business, and it is what I would focus on first. Aligning values is incredibly important for a company to flourish.
Q3. You have said there is a difference between founders who validate properly and those who do not. What does validation actually look like to you?
The challenge with validation is that there is no single framework that fits everything. It depends on the business, the market, the people, and their experience. In the past, I made the mistake of building products too early without validating them, which meant wasting development resources before removing enough of the risk. The mental framework I use with my team, and share whenever anyone asks, is simple: a startup carries a lot of risk at the beginning, and the job of a good founder is to reduce that risk at the lowest possible cost. If your first experiment means building a whole product that costs two million dollars, that is probably not the right approach, although it might be, depending on the industry and how much funding you have. There is no absolute right or wrong. The point is to remove risk as cheaply as possible along the way.
Q4. Can you give an example of an idea you thought you had validated, but had not?
With a previous company, we incubated several ideas. A few worked from the start without much validation, which gave us the false confidence that we were smart enough to make anything work. We did not really understand validation until we failed a few times. What we learned is that not all validation is the same; it’s an art. During COVID, the market for freelance professionals exploded, from coaches and personal trainers to mental and physical therapists. Our solution was to digitize these professionals for increased efficiency. A personal trainer, for example, might need an app to manage customers, send payment links, and view a calendar. We spoke to a few people; they said it was a good idea, and we took that as validation. But we were asking the wrong questions and getting the wrong answers. We built the product, and nobody wanted it because it was not the right problem to solve.
Q5. So how do you know when to kill an idea versus push through?
What I have learned is that killing ideas is not the problem; waiting too long to kill them is. That is where validation comes in. You validate quickly and cheaply, and you have to be brave enough to let things go. The way I decide is by reflecting on what I want from the business. Is the goal: a billion-dollar company, an exit, or a cash-flow business? That is the first criterion. The second is whether the journey still excites me and what the opportunity costs are. Even if it is a good idea, will it take me to the outcome I want, and will the journey be one I enjoy? Then I decide accordingly.
Q6. And when you've taken funding but the business isn't working, does honesty with investors get harder?
There are two cases. If you have raised funding and the business is successful, you will enjoy the journey because success motivates people. A founder who does not enjoy certain parts of a successful business can build the company around the areas that are energising. Success breeds motivation, not the other way around. If the business is not successful, motivation is usually low, and that calls for an honest conversation. I recently had a friend who had to close a funded startup, and I had told him two years earlier that he should reconsider. Investors appreciate an honest founder who returns the remaining money and says, “This is not working,” rather than spending what is left when it no longer makes sense. Founders worry that not finishing one journey will hurt their next raise, but I do not think that is the real issue. I have made angel investments, and I would rather back someone who has done it before and failed than someone who never has. Failure is the wrong frame; the real question is how much the person learned.
Q7. You share a banking partner, Ruya, with Alaan, and they launched their business account about two months before you. Being second isn't necessarily a problem, but how do you think about competing from there?
Many companies spend too much time worrying about competition and whether they are first or second. Look at Apple. They launched a foldable mobile device years after everyone else, and I am fairly sure they will be more successful with it. So that is not the benchmark. Our benchmark is whether we are meeting the needs of our ICP. Do we know who we are as a company? Are we solving the right problems for the right customers? That is what we measure ourselves against.
Q8. Does the funding gap matter, then? Alaan and Qashio have both raised more. Does that limit how fast you can grow?
Money is a utility at the end of the day. When we started, we were more funded than anyone else. Then we reached a stage where we were less funded, and I feel the team actually came together culturally during that period because we built a better company. We have used AI extensively to enable everyone, and we are three to four times more efficient than others in the market. Those are the moments when companies can shine and shift their mindset. My background is in tech, and tech people are intrinsically lazy in the best sense: if you ask them to automate, it excites them. Today, we launch products faster than many peers with a much leaner team. More headcount does not always mean more output. I am grateful we had less money at one point because that was when we sharpened our pencils and built a better company.
Q9. Between your earlier rounds and now, what are investors asking differently, and have there been investors you turned down?
Today, the narrative is more about whether your unit economics and fundamentals are right. Is the company simply burning money, or can it become profitable? We have proven that we are profitable, that we can still grow exponentially, and that we know who we are. The second question is where the journey goes: which markets we enter. Investors do not invest in the past; they invest in the future. Everything we have done so far is good, but the thesis has to be about where the company goes next. And yes, we have turned investors down. If there is no clear fit, or if someone does not understand how startups work and how Series A, B, and C rounds work, they can become the opposite of helpful, even if they are a big name. We focus on VCs with real experience who share our mindset.
Q10. Let’s talk about the team. You have described a three-person finance function on six-figure revenue, and a flat, ownership-driven structure. Can you tell us more about that?
I think we are well beyond six-figure revenue now. The point is that, instead of hiring many people, we hire the right people and help them use the tools around them efficiently. That makes us operationally faster. We close the month and get the report within two days; previously, with a larger team, it took two to three weeks. Picking the right people and enabling them with the right tools has been our strategy this past year. Average revenue per employee has tripled in the last year just from adopting these tactics. On structure, it comes down to full ownership and clear accountability. A couple of years ago, accountability was spread across peers, which made it hard for anyone to take ownership. In many companies, the C-level does not enable the management layer, so every decision goes upward and you end up with a few leaders and a lot of managers. We did not want that. We wanted everyone to be a leader, which meant giving people both the tools and the mindset to act with ownership. That is far more scalable. It also means reading teams individually: what motivates a tech team is different from what motivates a sales or operations team, so you find the win-win that unlocks accountability rather than assuming one culture fits all.
Q11. To wrap up, if a founder wanted to copy your discipline, what should they take and what should they leave?
Every founder has their own style, and I would tell them to focus on that, trust it, and go for it. That is the authentic story you should tell, rather than mimicking what you hear about Elon Musk, Sam Altman, or Jeff Bezos. It is about you as a founder: know your strengths, know your weaknesses, and build around them.
Building for the Long Run
In an industry often defined by who has raised the most, Pemo is trying to prove the opposite: that the company built to last is the one that can reach the same place with less. Ayham Gorani’s throughline is consistent: validate cheaply, kill quickly, stay lean, and let clear ownership and AI carry some of the load that headcount used to. That lean approach will face a bigger test as Pemo takes on the compliance and risk demands of holding customer funds. Still, Ayham Gorani seems less concerned with where the company sits in the funding rankings than with whether it keeps solving the right problems for the customers it set out to serve.
About Ayham Gorani
Ayham Gorani is Co-Founder and CEO of Pemo, a UAE-based spend management platform serving more than 6,000 businesses across the Middle East, North Africa and Pakistan. Born in Germany to Syrian parents, he trained as a computer scientist and built and sold his first company before moving to the UAE in 2011. Since founding Pemo in 2022, he has raised 19 million dollars across two rounds, led the company onto Forbes Middle East’s Fintech 50, and secured in-principle approval from the Central Bank of the UAE for a Stored Value Facilities licence. He is also an angel investor in early-stage startups.
Related Articles
Pemo Wins UAE Central Bank Approval to Close the SME Financing Gap
How Lalamove's First Year in the UAE Turned On-Demand Delivery Into SME Infrastructure
Saudi Fintech Abwab.ai Raises $4 Million to Expand SME Lending Platform
Related Articles